Is It a Good Time to Buy a House in Las Vegas?

Updated October 11, 2026. Based on September 2026 housing statistics and mortgage rates released October 8, 2026.
It can be a good time to buy a house in Las Vegas if the payment fits your budget and you plan to stay for several years. Buyers have more homes to choose from, and prices have eased from their summer peak. The challenge is financing: mortgage rates are higher than they were a year ago. That creates a market with potential negotiating opportunities, but affordability still requires a close look.
Here is what the latest available data means for your home search.
What Does the Latest Las Vegas Housing Report Show?
Las Vegas REALTORS® reported the following September figures for existing homes sold through its Southern Nevada Multiple Listing Service:
| Market measure | September 2026 |
|---|---|
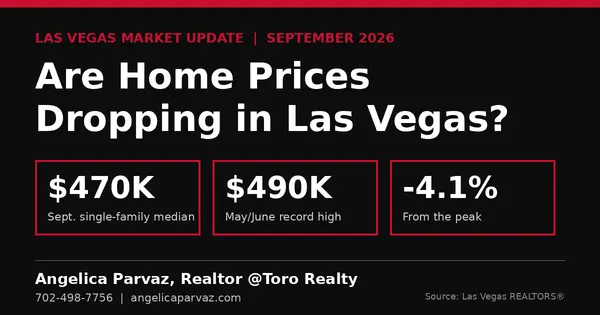
| Median single-family sale price | $470,000 |
| Change from August | Down 1.1% |
| Change from September 2025 | Unchanged |
| Median condo and townhome sale price | $290,000 |
| Single-family listings without offers | 7,995, up 6.6% year over year |
| Housing supply at September’s sales pace | Approximately five months |
The single-family median was $20,000 below the $490,000 record reached in May and June. That represents a decline of approximately 4.1%, calculated as $20,000 ÷ $490,000. These statistics do not capture all builder sales or homes sold directly by owners.
Buyers Have More Choices and Potential Negotiating Room
September single-family sales fell 7.4% from a year earlier, while housing supply increased from roughly four months to five months.
The practical interpretation is that buyers have more alternatives while sellers face a slower sales pace. Depending on the property, that may create an opening to negotiate the purchase price, repairs, or closing-cost assistance.
However, a softer market does not mean every seller will accept a large discount. Among single-family homes that sold in September, 75.9% sold within 60 days.
Recommended approach: evaluate each home against recent comparable sales, its condition, and competing listings before deciding what to offer.
Mortgage Rates Are the Biggest Affordability Challenge
Freddie Mac’s latest weekly survey reported a 7.40% national average for a 30-year fixed mortgage on October 8, compared with 6.30% a year earlier. This is a national benchmark, not a guaranteed Las Vegas loan quote. Freddie Mac’s survey focuses on conventional purchase loans for borrowers with excellent credit and 20% down payments.
To illustrate the effect, consider a $470,000 home with a 20% down payment:
- Down payment: $94,000.
- Loan amount: $376,000.
- Monthly principal and interest at 7.40%: approximately $2,603.
- Monthly principal and interest at 6.30%: approximately $2,327.
That is approximately $276 more per month for the same loan amount. These calculations use a fully amortizing, 30-year fixed loan with 360 monthly payments. They exclude property taxes, insurance, HOA fees, and maintenance.
The lesson: a lower sale price does not necessarily produce a lower monthly housing cost when interest rates rise.
When Buying Now May Make Sense
The Consumer Financial Protection Bureau recommends considering your income stability, ownership costs, emergency savings, and how long you expect to keep the home when deciding whether to buy.
A sensible buying decision starts with a few questions:
- Can you comfortably afford the full payment at the rate offered today?
- Will you have savings remaining after the down payment and closing costs?
- Can your budget absorb repairs and ongoing maintenance?
- Do you expect to stay long enough to justify the costs of buying and eventually selling?
The CFPB also recommends keeping money available for moving costs and an emergency cushion when determining your down payment.
If buying would exhaust your savings or leave you depending on a future refinance to afford the payment, waiting and strengthening your finances may be the better choice.
Should You Wait for Prices or Rates to Fall?
The current data cannot tell you when Las Vegas prices will bottom out or what mortgage rates will do next. LVR’s September release acknowledged uncertainty about the near-term direction of rates.
Recommended approach: make your decision using today’s purchase price, a current lender quote, and your expected ownership costs. Treat any future refinance or appreciation as a possibility rather than part of the affordability plan.
For a financially prepared buyer, today’s additional inventory and lower prices may create a worthwhile opportunity. Whether a particular home is a good purchase still depends on its price, condition, financing, and fit with your plans.
Thinking about buying in Las Vegas? Contact us to review recent neighborhood sales and available homes, then work with your lender to compare the full monthly cost before making an offer.
Categories
Recent Posts
"You deserve more than someone who just opens doors. I guide you from the first showing all the way to closing, so you feel good about every decision you make."